So you’ve hit your 40s or 50s and the retirement account isn’t exactly where you’d hoped. You’re not alone — not even close. A gap between what’s saved and what’s actually needed is surprisingly common at this stage. But here’s the thing: your 40s and 50s often bring higher income and fewer financial drains than earlier decades did. Kids may be out of the house. The mortgage might be shrinking. That opens real room to move. The window isn’t closed — and what you do now genuinely matters.
Take Full Advantage of Catch-Up Contributions
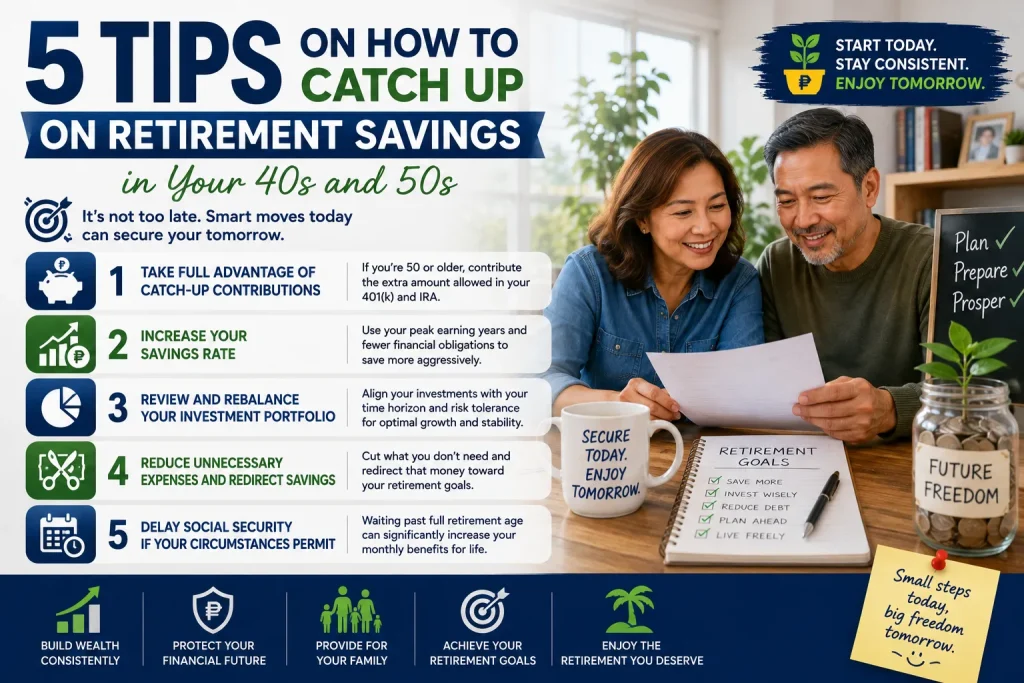
Hit 50? The IRS unlocks something younger savers simply can’t touch. Once you cross that threshold, you’re allowed to contribute extra amounts to retirement accounts on top of the standard annual limits — and those catch-up provisions exist precisely for situations like yours. A 401(k) lets you stash away an additional sum beyond the regular cap each year. IRAs offer their own catch-up allowances too. Max these out. You’re using a tool that’s unavailable to anyone under 50, which is a genuine structural advantage during a period when every dollar counts.
Increase Your Savings Rate When You Can
Peak earning years and shrinking obligations — that combination doesn’t come around twice. If your kids are independent or the mortgage is nearly done, the cash that used to disappear into those obligations can go somewhere more useful. Even modest contribution bumps compound hard over a decade. And windfalls? Bonuses, tax refunds, an unexpected inheritance — route those straight into retirement accounts before lifestyle inflation swallows them. It’s not about slashing your daily expenses. It’s about capturing money that’s already flowing through your hands.
Review and Rebalance Your Investment Portfolio
Your investment mix in your 40s and 50s needs to reflect two things simultaneously: how much runway you have left, and how much market turbulence you can genuinely stomach. Some people in this range park too much in conservative vehicles and quietly miss out on growth. Others are still running an aggressive strategy that made sense at 32 but feels shaky now. A real, honest look at your current holdings will tell you whether your allocation actually matches your retirement timeline and risk tolerance. Rebalance periodically — don’t just set it and forget it. And as assets grow more substantial during this phase, many people building estate plans alongside their retirement strategy turn to corporate trustee services to make sure wealth transfers happen with professional oversight and according to their actual wishes. Portfolio balance and estate structure aren’t separate conversations — working through both together helps you find the right equilibrium between growth potential and long-term stability.
Reduce Unnecessary Expenses and Redirect Savings
Look hard at recurring costs. Unused subscriptions, redundant memberships, utility bills that haven’t been renegotiated in years — these tend to quietly accumulate. Eliminating even a handful of them frees up real money each month without touching anything you actually enjoy. Consolidate streaming services. Refinance debt at a lower rate if you can. Switch phone plans. Done together, those moves can collectively unlock several hundred dollars a month. That’s not nothing. Over years, those small redirected amounts compound into something substantial — and it doesn’t feel like deprivation, because you’re cutting spending that was delivering little benefit anyway.
Delay Social Security If Your Circumstances Permit
Every year you wait past full retirement age, your Social Security benefit grows. The monthly number climbs — meaningfully. If you’ve got enough saved or other income to bridge early retirement without it, waiting can result in dramatically higher lifetime payments. This strategy makes particular sense if longevity runs in your family or if you want Social Security to anchor the income side of your plan. That said, it’s not one-size-fits-all. Your health, your family situation, your overall financial picture — all of it needs to factor in before you decide.
Conclusion
Behind on retirement savings at 45 or 52? That’s not a verdict. Catch-up contributions, peak earning potential, smarter allocation, trimmed expenses, delayed benefits — these aren’t abstract concepts. They’re levers. Each one addresses a different piece of retirement readiness, and you don’t have to pull all of them at once. Even acting on two or three can shift the trajectory in a real way. The time remaining before retirement is shorter than it was — but it’s still enough to make substantial progress, provided you start moving now and stay consistent about it.